
Poultry
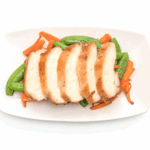
Chicken production remains broadly available, but value is shifting within the category. Chicken slaughter last week was roughly 2% ahead of a year ago, and for the week ending August 8, production increased 1% versus the prior week. Still, output was 1.2% below the same week last year, driven entirely by a 1.7% decline in bird weights. On a year-to-date basis, production is still running 2.4% ahead of last year, supported by better bird availability. Broiler egg sets and chick placements are also tracking about 1% above year-ago levels, although growth has slowed. In the market, pricing was mostly soft, with breast meat, tenders, and wings lower, while whole birds and leg quarters were the main exceptions. The bigger story continues to be dark meat strength: in July, boneless skinless thighs hit a record premium over boneless skinless breasts for the month, supported by both exports and stronger domestic dark-meat consumption.
Outlook: Dark meat should remain a relative strength near term, though stronger white-meat demand later this year could begin to narrow that historic pricing gap.
Beef
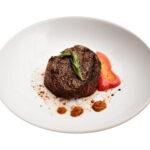
Beef markets firmed last week, but larger demand concerns are still building. Production increased 1.3% week over week and came in just 1.4% below the same week last year, yet year-to-date output remains down 5.5% because cattle slaughter is running 8% below last year. The USDA Choice boxed beef cutout rose 1.8% last week and Select increased 0.6%, led by gains in briskets, loins, and choice ribs. Even so, cutout values remain about 5% below 2025 levels. On the consumer side, resistance to elevated beef pricing is becoming more visible, with the USDA lowering its 2026 per capita beef consumption estimate to 58.9 pounds per person, down 0.5% year over year. Trade data adds another layer: June beef exports fell 10%, while imports jumped 24%, setting a monthly record. Imported lean beef trim continues to trade well below comparable domestic product, and U.S. beef imports from Mexico are running at a record pace year to date.
Outlook: Tight domestic supply should keep beef fundamentally supported, but record imports and growing consumer resistance to high prices will likely limit how far the market can move higher.
Pork
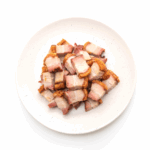
Pork remains one of the more frustrating protein categories, with lower relative pricing still failing to generate much demand momentum. Last week, pork output rose 2.2% from the prior week but was 1.5% below the same week last year. Year-to-date production is up just 0.4%, supported by 1.1% heavier carcass weights, while summer production is still expected to track about 2% below 2025. Despite that, the USDA pork cutout moved lower last week, pressured by declines in ribs and hams. Loins and bellies were the only primals higher, with bellies approaching their most expensive levels in a year. Demand remains the issue: USDA lowered its 2026 domestic pork per capita consumption estimate, and 2026 consumption is expected to come in near the lowest level in a decade. Export performance has also been soft, with June pork exports down 4% year over year, though hams to Mexico remain a bright spot, up 1% year to date to a record high. Domestic ham prices are tracking about 6% below last year.
Outlook: Seasonal weakness and sluggish demand suggest pork, especially hams and ribs, could face additional downside pressure heading into fall.
Produce
Produce remains one of the quieter corners of the market, but avocados are the clear watch item. Last week, prices across the major produce categories were mostly unchanged, with lettuce and tomatoes flat week over week. 48-count Hass avocados were also essentially flat, but that stability could be temporary. The USDA’s suspension of avocado inspections in Michoacán, Mexico, the largest supplier of avocados to the U.S., introduces meaningful supply risk if the security issue behind the halt is not resolved quickly. Potatoes continue to rise as expected and now look positioned to reach 2025 highs as soon as this week, although that move has largely tracked seasonal expectations.
Outlook: Most produce items should remain stable in the near term, but avocados carry the greatest upside price risk if inspection disruptions in Mexico continue.
Dairy
Dairy markets were mixed last week, with cheese continuing to stand out. CME spot activity was light, but weekly averages moved higher for cheese blocks, cheese barrels, and nonfat dry milk, while butter and dry whey softened. Milk production remains seasonally light, but cream supplies are available and butter inventories are sufficient, which continues to weigh on butter values. On the demand side, cheese remains well supported, helped by strong retail promotion and very strong export movement. In June, U.S. cheese exports rose 24% from a year ago to a fresh record. That strength was helped by competitive U.S. pricing, with the June CME cheese block average the second-lowest for the month in more than a decade, making U.S. cheese highly attractive in global markets.
Outlook: Cheese should stay well supported by exports, but without a broader recovery in global markets, a major sustained move higher in domestic cheese pricing still looks unlikely.
Grains
Grain markets were relatively quiet outside of corn, but wheat risk continues to build under the surface. Wheat prices briefly softened after reports that Ukraine proposed a mutual halt on attacks against commercial shipping in the Black Sea and Sea of Azov, but Russia rejected the proposal, leaving the market back in uncertainty. This matters because August is a critical export period for the region, and prolonged shipping disruptions could tighten global supply flows. More concerning for operators with long-term procurement exposure, there are growing reports that farmers may not have enough income to properly prepare for the 2026/27 planting season, turning what began as a short-term logistics issue into a possible longer-term production concern.
Outlook: Unless Black Sea shipping tensions ease soon, wheat appears to retain meaningful upside price risk from both current export disruption and future planting uncertainty.
Seafood
Seafood pricing was generally calmer in the latest June import data, but cod remains the exception and the standout concern. Across the six seafood items tracked most closely, none moved more than 7% month over month, except for frozen cod fillet. Cod prices rose another 5% in June, extending a four-month rally that has pushed average pricing up nearly 52% during that stretch. Even more notable, cod has set a new all-time high every month of that rally, with data going back to 2013. The good news is that import volumes improved for a second straight month, although they still haven’t fully returned to normal seasonal levels. If those volumes continue improving through the end of the year, supply pressure should gradually ease.
Outlook: Cod prices may stay elevated near term, but improving import volumes should help cap the rally within the next month or two and create room for relief later this year.